


Summary
The Asia Pacific telecom sector's second-quarter 2025 performance shows an industry moving decisively beyond connectivity-only economics toward ecosystem monetization, cost discipline, and frontier infrastructure investment. Across mobile, broadband, and enterprise ICT, operators are converting scale and service breadth into topline and margin performance amid currency and political volatility in select markets.
Profitability trends reveal a widening split between scale players extracting margin from ecosystem breadth and mid-tier operators relying on disciplined cost control, while cyber incidents and foreign exchange swings increasingly shape EBITDA outcomes alongside operational execution. Capital allocation patterns show 5G rollout spending tapering as networks near completion, with capex redirected toward AI-ready, cloud-integrated infrastructure and fibre expansion positioned to support enterprise, cloud, and generative AI workloads.
ARPU trends diverge sharply based on tariff discipline, postpaid migration, and regulatory pricing ceilings, while data-led consumption offers partial insulation in emerging markets. Frontier innovations, including AI-powered cloud platforms and generative AI-ready data centres, are reshaping the competitive structure of telecom across the region.
- Revenue, EBITDA, capex, and ARPU benchmarking across dozens of APAC telcos
- Capital allocation shift from 5G rollout to AI-ready and fibre infrastructure
- Divergence between ecosystem-led and connectivity-only operators
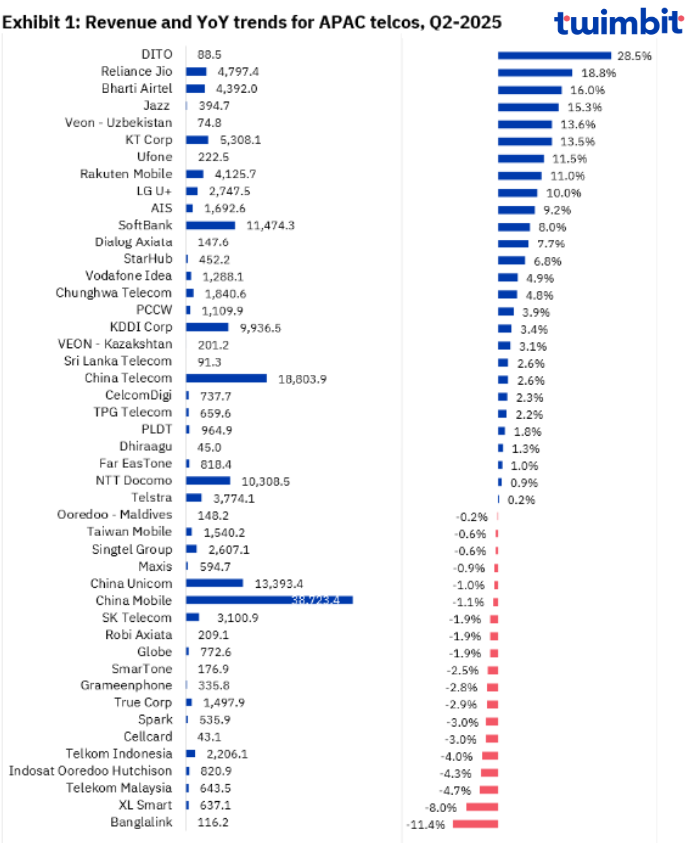
Which APAC operators are converting ecosystem scale into durable revenue and margin advantage?
Schedule a call with Twimbit analyst to learn how we can help you.
Already a Twimbit client? Log in